The world of digital currencies and stablecoins is evolving rapidly, and it's an exciting time for those who want to see these assets become more mainstream. The latest research reveals some fascinating insights into how consumers are embracing these new forms of money, and it's clear that the potential for growth is immense.
The Checkout Challenge
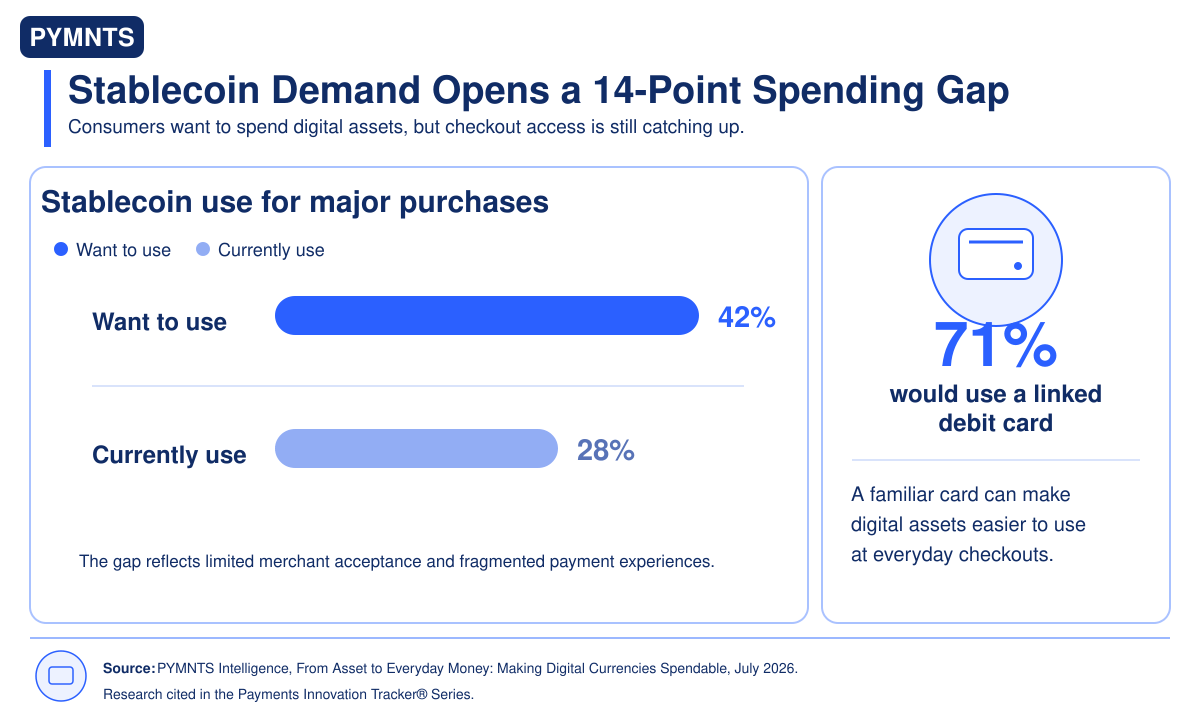
While digital assets are gaining traction, there's a notable gap between consumer interest and actual usage. The report highlights a 14-percentage-point difference between the number of stablecoin holders who want to use these assets for major purchases and those who are already doing so. This suggests that the challenge lies not in generating curiosity but in providing the necessary infrastructure and convenience.
A Familiar Path to Adoption
One of the most intriguing findings is the preference for familiar tools. A significant majority of stablecoin holders (71%) would opt for a linked debit card to spend their digital assets. This approach simplifies the process by converting digital assets at the point of sale, leveraging established card networks, and paying merchants through familiar systems. It's like a seamless upgrade to the payment experience, where the underlying technology evolves without disrupting the user's comfort.
Trusting the Familiar
Trust is a critical factor in the adoption of any new financial technology. The report indicates that a vast majority of consumers (77%) would prefer to access crypto or stablecoin wallets through their existing banking or FinTech apps. This preference for familiarity extends beyond convenience; it's about feeling secure and understood by providers who already manage their money. By leveraging this trust, banks and FinTechs can make digital assets more accessible and less intimidating.
Beyond Consumer Checkout
The potential for digital assets extends far beyond individual consumer transactions. The report highlights the rapid growth of monthly crypto card spending, which has increased by about 15 times since early 2023, reaching an annualized rate of approximately $18 billion. Stablecoins are also making inroads in cross-border business payments, offering faster settlement, lower costs, and access to dollar-denominated value. These developments showcase the versatility and potential of digital currencies beyond personal finance.
Addressing Barriers
Despite the promising outlook, there are still barriers to widespread adoption. Limited merchant acceptance, transaction costs, volatility, and fraud concerns are cited as significant challenges by nearly half of surveyed consumers. Overcoming these obstacles will require a collaborative effort between regulators, financial institutions, and technology providers to create a robust and secure ecosystem.
A Positive Outlook
The report's measured optimism is well-founded. By leveraging linked cards, real-time conversion, and modern issuer processing, the industry can make digital assets more accessible without forcing consumers or merchants to adopt entirely new payment methods. This gradual integration strategy respects the existing financial infrastructure while embracing the innovations of the digital age.
In my opinion, the key to unlocking the full potential of digital currencies lies in striking a balance between innovation and familiarity. By building upon the trust and infrastructure of traditional finance, we can create a seamless transition to a more inclusive and efficient digital economy. It's an exciting journey, and I, for one, am eager to see how this story unfolds.